Lifestyle creepHow former luxuries become necessities
Lifestyle creep, also known as lifestyle inflation, is a pattern where spending rises at the same rate as income, turning former luxuries into perceived necessities. It happens quietly through small, routine upgrades rather than sudden splurges. Because spending keeps pace with higher earnings, a household's ability to save money stalls even as their paychecks grow.
By the edgi team We find the most surprising true thing about an idea and build a 60-second lesson around it.
A raise almost never arrives as one big number. It arrives as a slightly larger amount landing every two weeks, which is exactly the shape of a rent, a lease or a subscription. So that is what it buys. A bigger flat, a newer car, delivery instead of the shop, one more service billed monthly. Each of them is small and defensible on the day.
Lifestyle creep is the sum of them. Nothing dramatic happens; the cost of an ordinary month goes up, and economists have called that one-way movement a ratchet since 1949.
Why it only turns one way
Upgrading takes an afternoon. Downgrading takes a move, a sale, a conversation with a landlord, and a visible step backwards in front of everyone who watched the upgrade. Some of it is contractual. The average new car payment in America runs about $748 a month, on a loan of roughly 69 months. Signing takes an hour and commits close to six years.
Housing is heavier still, because it sets the things around it. Where you live decides the commute, whether the commute needs a car, and which shops you walk past every day. So the flexible half of your spending keeps being converted into the fixed half. The income rose. The room to manoeuvre did not.
What it looks like from inside
The payslip climbs a long way and the feeling stays put, which is how a six-figure income and a permanent sense of being short end up in the same household. The pleasure of any one upgrade fades within weeks, which is the hedonic treadmill doing its ordinary work. The payment it created runs for years, one reasonable yes at a time.
The raise that survives is the one given a job before it landed. Once it has arrived and been absorbed there is nothing left to assign, and the month just costs more.
How lifestyle creep works
Lifestyle creep occurs when an increase in discretionary income leads directly to higher living costs. This increase in available cash comes from two main sources: earning more money through career advancements, or shedding large expenses like paying off a mortgage or finishing the costs of raising children.
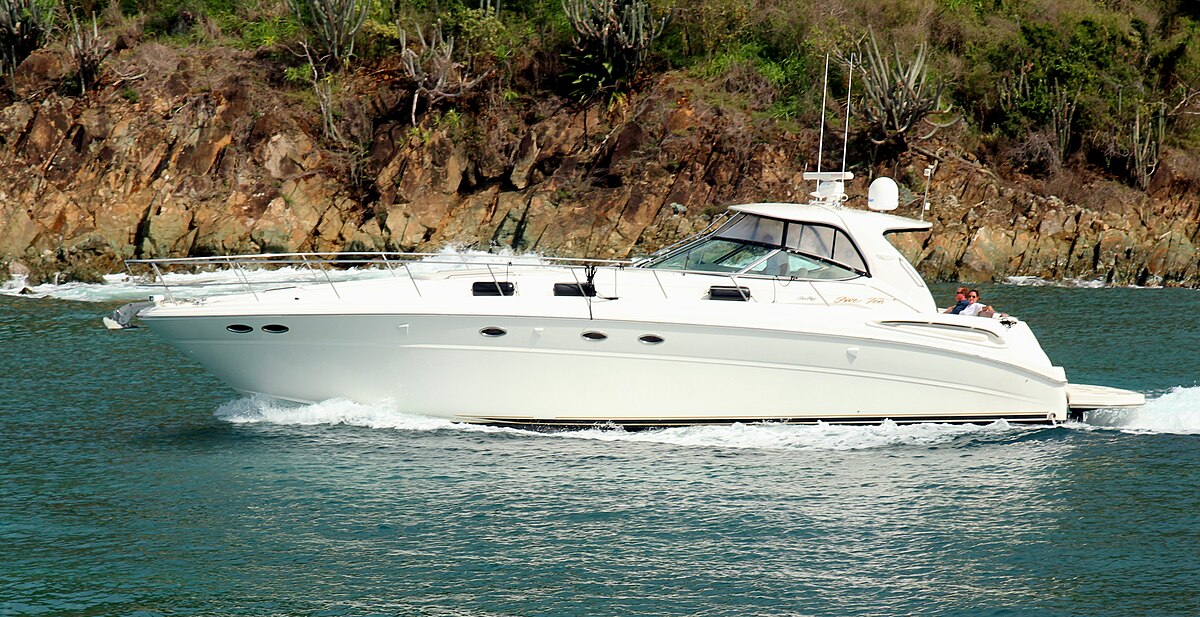
Motorboats and other luxury goods represent the kind of expensive purchases that often accompany higher discretionary income. Prayitno / Thank you for (12 millions +) view from Los Angeles, USA, CC BY 2.0, via Wikimedia Commons
Instead of going into savings, the extra funds shift toward things that were once unaffordable. This includes purchases with ongoing maintenance costs, such as expensive vehicles, a second home, and club memberships. Over time, the flexible part of a budget turns into permanent fixed commitments.
Experts call this pattern silent inflation because it happens subtly. Because people adjust their baseline upward with every new purchase, the cost of an ordinary month rises without feeling like a major change in habits.
Why it is hard to reverse
Economists have compared this one-way spending shift to a ratchet. Upgrading a lifestyle takes very little time, but downgrading requires breaking long commitments, selling property, moving, or taking a visible step down in front of peers.
Much of this spending is locked into multi-year contracts. For example, the average new car payment in America is about $748 per month on a loan lasting roughly 69 months. Signing the contract takes an hour, but it locks up cash flow for nearly six years. Housing choices create an even stronger anchor, setting fixed daily costs for commutes, vehicles, and neighborhood shopping.
The initial pleasure of an upgrade fades within weeks due to the hedonic treadmill. While the emotional lift disappears quickly, the monthly bills stay behind for years.
Who is most vulnerable
Lifestyle creep is common among young adults in their mid-twenties to early thirties. Rapid career growth gives this group more discretionary income, which frequently leads to buying expensive gadgets and goods to project social status and fit in.
It also creates severe risks near retirement age, when people reach their peak earning years and drop major child-rearing costs. If someone builds an expensive lifestyle right before leaving the workforce, trying to maintain that lavish standard on a fixed retirement income causes financial strain.
Test yourself
A $5,000 holiday, or $400 a month more rent. Which does more damage?
The rent, because it passes $5,000 inside thirteen months and keeps going. The holiday is the bigger number today and then it is over. The rent is the smaller number forever, and it is also the one you cannot undo without moving house.
Someone's income doubles and they feel no less stretched. Most likely reason?
Because their fixed monthly costs rose alongside the income. All three would explain the feeling. Only one explains why the money is genuinely gone by the end of every month rather than sitting somewhere they could reach it.
Play the lesson in edgi and the card is yours. It lands on your Map next to the ideas it connects to, and turns from matte to foil to gold as you learn more around it.
The clearest signs are difficulty saving money and accumulating debt despite earning a higher income. When pay increases fail to create extra breathing room at the end of the month, lifestyle creep is usually the cause.
How can you prevent lifestyle inflation?
The standard solution is to make a budget and set clear limits on expenses. Assigning a specific savings job to a raise before it arrives prevents the extra money from being absorbed into ordinary monthly spending.
Is lifestyle creep contagious?
Yes, lifestyle creep spreads as people compare their standard of living with peers. Social comparison often drives individuals to purchase expensive items to project status and match the lifestyle choices of those around them.